Category: Latest Posts

  • Here’s how Carney’s $2 billion home retrofit program works

    Here’s how Carney’s $2 billion home retrofit program works

    A $2-billion rebate program will offer up to $10,000 per household to encourage Canadians to switch to electric cold-climate air-source heat pumps. The program, spanning eight years, aims to support up to 820,000 homeowners, promising lower energy bills, year-round comfort, and reduced emissions. Income-based rebates range from $2,000 to $10,000, with no energy audits required. Applications will be online with quick approval and payment.

    Continue to full article

  • Buying a house before you move here? NS making deed transfer tax easier to deal with

    Buying a house before you move here? NS making deed transfer tax easier to deal with

    Nova Scotia is updating its non-resident deed transfer tax rules to support permanent movers. Changes include extending proof-of-residency from six months to one year, clarifying extension conditions, exempting inherited property for non-residents, extending refund application time to two years, and allowing refunds to legal representatives. The 10% tax applies to residential properties with up to three units. In 2025-26, $18.4 million was collected from 1,791 transactions.

    Continue to full article

  • Leaving your mortgage renewal too late narrows your options

    Leaving your mortgage renewal too late narrows your options

    Homeowners approaching mortgage renewal should start the process months in advance to avoid limited options and higher costs. Fixed rates have risen, with many facing payment increases around 20%. Early preparation allows securing rate holds, gathering financial documents, and comparing options beyond just rates, including prepayment privileges and penalties. Waiting too long may force rushed decisions and less favorable terms.

    Continue to full article

  • Nova Scotia Offers Two Paths for First-Time Buyers

    Nova Scotia offers two main paths: an interest-free 5% down payment loan, or a credit union mortgage needing only 2% to 4% down.
    The provincial loan is interest-free and repaid over 10 yr, with household income below $145K and regional purchase caps of $570K, $375K, or $300K.
    The credit union mortgage allows 2% to 4% down, skips default insurance, and fits households with income below $200K or credit between 630 and 650.
    New builds may unlock a provincial HST rebate up to $3K, but buyers still owe municipal deed transfer tax, usually 0.5% to 1.5%.
    The two provincial routes are alternatives, but federal savings, retirement withdrawals, tax credits, and the federal HST rebate can generally be layered on.

  • HAUNTED WALK THROUGH

    HAUNTED WALK THROUGH

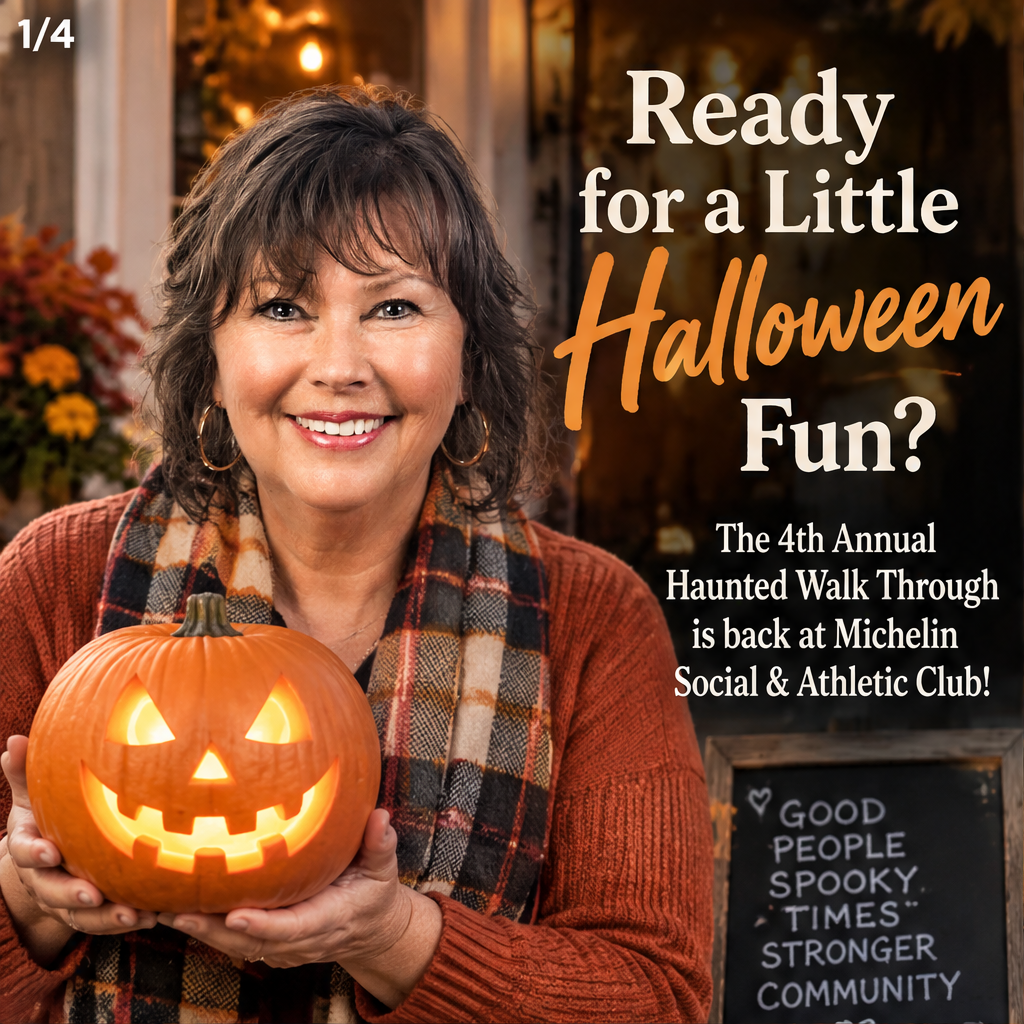
    Get ready for a memorable Halloween outing in Bridgewater! The fourth annual Haunted Walk Through is coming to Michelin Social & Athletic Club on October 29–30, offering local families and thrill-seekers a fun way to celebrate the season together.

    Families with younger children can enjoy a kid-friendly experience from 5:00–5:45 p.m. It is a great opportunity for little ones to take part in the Halloween excitement while keeping the scares more suitable for them.

    For those looking for a bigger fright, the full-fright experience runs from 6:00–8:00 p.m. Bring your bravest friends, embrace the spooky atmosphere, and make an evening of this popular community event.

    Mark your calendar and visit https://yoursouthshore.ca/events/haunted-walk-through/ for event details. As your local Bridgewater real estate professional, I love sharing community highlights that make life in the South Shore so special—especially when they bring neighbours together for a little Halloween fun!

    Continue to full article
  • Canada Condo Buyers: Evaluate the Building First

    Canada’s softer condo market gave buyers more time, more inventory, and more negotiating leverage, making building-level due diligence just as important as unit price.
    In Ontario, every condo offer should stay conditional on reviewing the Status Certificate, because reserve funds, litigation, fees, and rules can shape long-term value.
    Buyers should compare reserve fund balances with the reserve fund study and watch for repeated fee jumps above 5%, which can signal deferred maintenance.
    Investor-heavy buildings can affect financing, while transit access, walkability, retail, and comparable sales in the same building help test long-term fit for buyers.
    With prices lower and choice higher, the main risk is not overpaying for a strong building but underpaying for a poorly run one.

  • The Role of Supply and Demand in Real Estate Pricing

    The Role of Supply and Demand in Real Estate Pricing

    The housing market is influenced by supply and demand, where high demand and low supply drive prices up, often causing bidding wars. Low interest rates increase demand by making mortgages more affordable, while supply fluctuates due to factors like new construction, population changes, and disasters. The 2000s housing crash resulted from high demand fueled by low rates and relaxed lending, followed by oversupply and falling prices. Understanding these dynamics helps predict market trends.

    Continue to full article

  • When is the right time to buy?

    When is the right time to buy?

    Many people wonder when the "right time" to buy a home truly is. In my experience working with clients throughout Nova Scotia, I’ve seen that most Canadians focus on their own readiness and financial comfort rather than trying to time the market. Steps like getting your mortgage pre-approval, having honest conversations with trusted advisors, and building a solid financial plan make all the difference—these are the foundations for moving forward with confidence. Mortgage protection insurance is also a key piece for long-term stability. My priority has always been to help buyers and sellers feel informed and secure in their decisions, every step of the way.

    Continue to full article

  • Rent or buy: When does homeownership actually make financial sense?

    Rent or buy: When does homeownership actually make financial sense?

    One of the most common questions I hear is, “Should I rent or buy?” There’s no one-size-fits-all answer—homeownership does offer the chance to build equity, but the high upfront and ongoing costs can make it tough for many to get started. On the other hand, renting can help you avoid those initial expenses, yet rising rents often make it hard to save. In my experience helping clients throughout Bridgewater and beyond, I’ve found that true affordability comes down to understanding what you can comfortably manage each month—including every expense—and still keep your financial safety net intact. If you’re wondering which path is right for you, it’s all about balancing your goals with your budget.

    Continue to full article

  • Canada’s MLS® HPI Tracks Home Price Trends

    As a REALTOR® in Bridgewater, I often get asked how we keep track of changing home prices in our local neighborhoods. Canada’s MLS® Home Price Index (HPI) is one of the tools I rely on to provide clients with a clearer, more accurate picture of market trends. Instead of just looking at average or median prices, the HPI goes deeper by tracking how buyers actually value different home features—so we get a steadier, more meaningful sense of price changes over time. Each month, the HPI draws on over 20 years of listing data and advanced statistical models to define what a 'typical' home looks like in a given area. By following these benchmark homes across various neighborhoods and property types, I’m able to spot emerging trends and offer well-grounded advice. My goal has always been to help buyers and sellers make informed decisions with confidence, and tools like the HPI are an important part of that process.